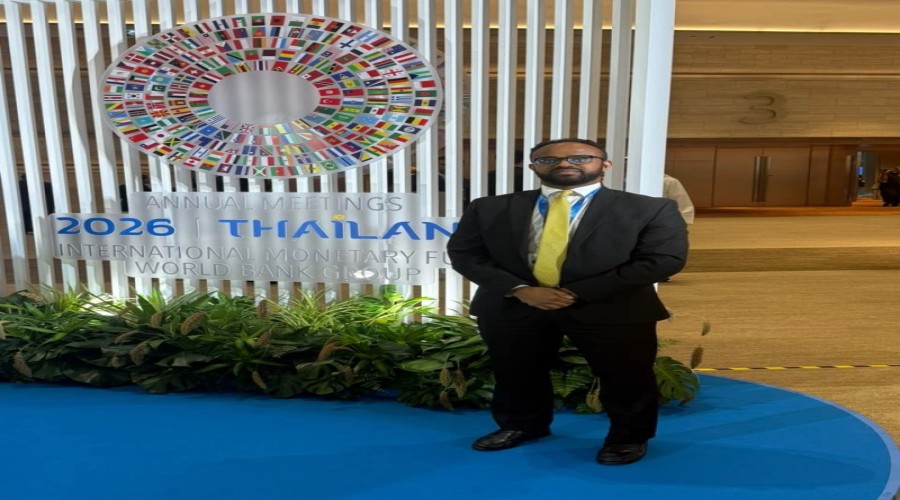
By: Nana
Appiah Acquaye
Somalia’s Ministry of
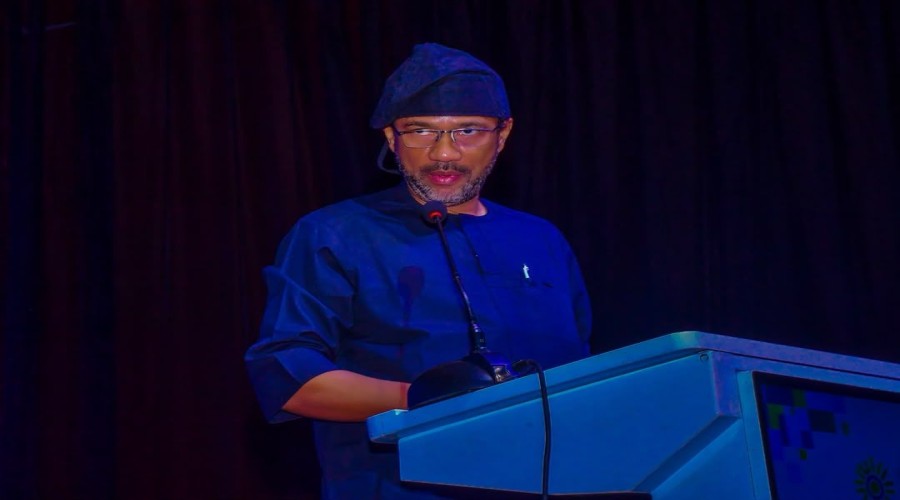
Finance official Liban Obsiye has highlighted climate finance, debt
sustainability, private capital mobilisation and regional integration as key
priorities for building a more resilient economy, following the conclusion of
the IMF and World Bank Annual Meetings in Bangkok, Thailand.
Reflecting on the global
economic outlook, Obsiye said he left the meetings with “more questions than
answers,” warning that uncertainty had become the new normal as artificial
intelligence (AI), climatic and geopolitical shocks, trade uncertainty and higher
sovereign debt burdens weakened national balance sheets and restricted
governments’ capacity to respond.
“The phrase macroeconomic
stability and words like growth, jobs and international cooperation were the
buzzwords at the Meetings. Yet, solutions were in short supply,” he said.
Obsiye identified three
developments that offered hope, including growing recognition of climate change
as a major challenge to global macroeconomic stability, sustainable development
and debt sustainability, particularly for countries facing its impacts without
meaningful financial assistance.
He stressed that climate
security in Somalia was not simply an environmental issue but one involving
economic security, social stability and national security.
“This recognition must be
followed by sensible, accessible and affordable solutions, especially for the
most fragile states in the world like Somalia,” he said.
Obsiye also welcomed the
World Bank’s prioritisation of support for micro, small and medium-sized
enterprises (MSMEs) as financial systems transform. He said these businesses
had significant potential to generate jobs, support growth and contribute to community
development.
He called for improved
access to credit, fair competition rules, a better-skilled workforce and
policies that enable businesses to benefit from public procurement
opportunities.
On development financing,
Obsiye said private capital mobilisation needed to play a much bigger role,
particularly in fragile states where conventional risk assessments could make
viable investments prohibitively expensive.
“We need to find better ways
of sharing risk and crowding private capital into these markets,” he said.
He further highlighted the
importance of raising domestic revenues, strengthening public financial
management, improving public investment and protecting social spending despite
global economic uncertainty.
Regional integration,
resilient infrastructure and diversified trade routes and markets were also
identified as measures that could help countries better absorb economic shocks.
“For Somalia, resilience,
debt sustainability, private capital mobilisation and regional integration are
not separate agendas,” Obsiye said. “They are all part of the same challenge:
building a more resilient economy that can withstand shocks and create opportunities
for its people.”
He also congratulated the
government and people of Thailand for hosting the meetings, recognising their
hospitality and assistance during his stay.
“I want to congratulate the
government and people of Thailand for hosting such an important event. I also
recognise their gracious hospitality and kind assistance throughout my stay,”
he said.