By: Robert Kwaku Annor
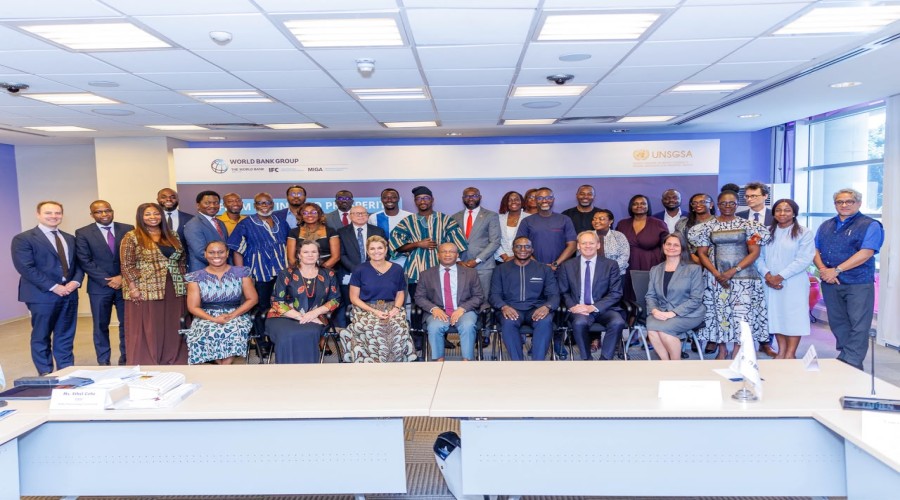
The World Bank Group has convened Her Majesty Queen Máxima of the
Netherlands, the United Nations Secretary-General's Special Advocate for
Financial Health (UNSGSA), alongside senior representatives of government,
regulatory institutions and the financial sector for a high-level roundtable on
expanding savings opportunities, pension coverage and access to capital markets
for informal-sector workers.
Held at the World Bank Group’s Accra office under the theme “From
Savings to Prosperity: Informal-Sector Pensions, Financial Health, and Capital
Markets”, the roundtable, organised jointly by the World Bank and the
International Finance Corporation (IFC), explored practical approaches to
strengthening household financial resilience while mobilising domestic savings
for productive investment.
The engagement forms part of broader efforts to advance financial
inclusion beyond access to financial services, towards enabling individuals and
households to build savings, manage financial risks and secure their long-term
financial wellbeing.
Ghana has made significant progress in expanding financial
inclusion, with 81 percent of adults holding a financial account in 2024,
compared with 58 percent across Sub-Saharan Africa, according to Global Findex
2025. Mobile-money access reached 78 percent.
However, significant gaps remain in household financial resilience
and retirement preparedness. Only 30 percent of adults could cover more than
two months of expenses following the loss of their main source of income, while
just 18 percent saved formally for old age.
Against this backdrop, Queen Máxima highlighted the importance of
integrating savings, insurance, pensions and other financial services to help
individuals move beyond account ownership towards greater financial security.
“Financial access is a critical enabler, but we must also look at savings,
insurance, pensions, and broader financial resilience,” she said.
She emphasised that emergency savings are particularly important in
sustaining long-term retirement contributions, noting that immediate financial
pressures often make it difficult for households to prioritise future needs.
“It is difficult to focus on retirement 30 years from now if you are worried
about a financial emergency tomorrow,” Queen Máxima said. She also underscored
the commercial relevance of financial health, describing it as a business
imperative rather than simply a corporate social responsibility concern.
Strengthening partnerships for financial health
Nathalie Kouassi-Akon, IFC Division Director for West Africa Gulf
of Guinea, said the roundtable provided an opportunity to build on Ghana’s
progress in expanding financial access and strengthening its financial system,
while addressing the remaining gaps in household financial security. “Financial
inclusion, while essential, is not the finish line. The real measure of success
is whether people are able to build resilience, withstand shocks and improve
their financial wellbeing over time,” she said.
She said Queen Máxima’s engagement came at an important time as the
World Bank Group advanced its Country Partnership Framework for Ghana,
providing an opportunity to align ongoing development efforts with the
country’s evolving financial sector priorities.
She further highlighted the importance of collective action
involving regulators, pension providers, investors, financial institutions and
innovators to identify scalable solutions and translate the discussions into
practical commitments. “Our hope is that this conversation will lead not only
to valuable insights, but also to practical actions and partnerships that help
more Ghanaians move from financial vulnerability to financial security, and
from savings to prosperity,” she said.
Expanding savings opportunities for informal workers
A central focus of the roundtable was the need to develop financial
products that reflect the income patterns and circumstances of informal-sector
workers, many of whom rely on irregular or seasonal earnings and remain
underserved by conventional savings and pension arrangements.
Participants explored opportunities to expand flexible
micro-pension models that allow contributions on a daily, weekly, monthly,
seasonal or lump-sum basis. Mobile-money platforms, agent networks and trade
associations were identified as important channels for improving access and
making regular saving more convenient. The discussions also highlighted the
importance of connecting long-term savings with appropriate insurance,
emergency liquidity and responsible credit to help households manage unexpected
financial pressures without compromising their retirement plans.
In addition, participants examined ways to broaden access to
capital markets through safe, regulated and professionally managed investment
opportunities, particularly for informal-sector and first-time investors.
Connecting domestic savings to productive investment
The roundtable also examined the role of pension savings and other
domestic financial resources in deepening Ghana’s capital markets and expanding
long-term financing for productive sectors.
Ghana’s three-tier pension system currently holds approximately
US$11.5 billion in assets, although participation among informal-sector workers
remains modest. Expanding coverage could strengthen the domestic institutional
investor base and increase the pool of long-term capital available to support
businesses and infrastructure development.
Through the Joint IFC-World Bank Capital Market Program (J-CAP),
the World Bank Group is working with the Government to strengthen capital
market foundations, diversify the institutional investor base and expand the
supply of suitable investment assets.
The programme also supports demonstration transactions in
infrastructure, green finance and small and medium-sized enterprise (SME)
financing, with the objective of creating additional opportunities to channel
domestic savings into productive investment. The World Bank Group is also
supporting the development of Ghana's new financial inclusion strategy, which
provides an opportunity to strengthen coordination across the financial sector
and advance a more comprehensive approach to financial health.
Strengthening the financial health ecosystem
The roundtable identified several priorities for advancing
financial health and expanding savings opportunities among underserved
populations. These include developing affordable and flexible financial
products that accommodate irregular incomes; expanding digital platforms that
reduce the cost and complexity of saving and investing; and strengthening
consumer protection, transparency and trust across financial services.
Participants also emphasised the need for safe and regulated
channels through which long-term savings can be mobilised for productive
investment, supported by a broader range of credible investment opportunities.
Continued collaboration among government, regulatory institutions, financial
service providers, the private sector and development partners will be
essential to advancing these priorities and ensuring that financial inclusion
translates into improved financial security for individuals and households.